
Term insurance is a simple, low-cost life insurance product designed to protect your family’s financial security if you are not around. You pay a premium for a fixed number of years (policy term), and your family receives the life cover (sum assured) if you pass away during the term.
Understanding what your term plan covers, and how your needs change over the years, can help you choose the best term insurance plan for your family.
What Term Insurance Covers and What It May Not
A standard term insurance plan usually provides:
- A lump-sum life cover if the life assured dies during the policy term
- Protection for a fixed duration, such as 20, 30, or even more years
- Coverage at comparatively low premiums, especially when bought young
However, term insurance may not:
- Pay any maturity benefit if you survive the policy term (pure protection plans)
- Cover deaths due to excluded causes (for example, some specific conditions, situations, or non-disclosure of health facts)
- Automatically cover critical illnesses, accidental disability, or income loss unless you add suitable riders
This is why it’s important to read your term insurance policy document, understand the coverage and exclusions, and decide if you need riders for extra protection.
What Makes A Term Plan Suitable For Your Family
The best term insurance plan for your family is not just the cheapest; it is the plan that fits your life, goals, and budget. A suitable term plan typically offers:
- Adequate life cover: Enough to replace your income, repay loans, and fund key financial goals for your family
- A policy term that matches your working years: Ideally until your major financial responsibilities reduce (for example, children finishing education or loans getting paid off)
- Affordable premiums: A term insurance premium that you can pay comfortably every year without straining your cash flow
- Flexible payout options: Lump-sum, monthly income, or a combination, depending on how your family may handle money best
- Relevant riders: Such as accidental death benefit, disability cover, or critical illness riders, based on your needs
When you match the cover, policy term, and premium to your real-life responsibilities, you move closer to the right term insurance for your family.
Estimate The Term Cover Your Family May Need
Income, Expenses, Liabilities, Goals, And Existing Cover
To estimate how much term insurance you need, start with a clear view of your financial life:
- Your incomeThink about how many years your family would need an income replacement if you were not there. This often links to your children’s age, your spouse’s income, and your retirement plans.
- Monthly expensesInclude household costs, rent or EMIs, school fees, medical costs, and lifestyle expenses. Remember that inflation will increase these over the years.
- LiabilitiesConsider home loans, personal loans, vehicle loans, or education loans. Ideally, your term insurance cover should be large enough to close these liabilities.
- Future goalsMajor goals like children’s higher education, marriage, or caring for ageing parents need to be factored in when deciding your life cover.
- Existing life insurance and assetsDeduct any existing life insurance coverage, employer-provided life cover, and easily accessible financial assets from your required cover to avoid duplication.
The gap between what your family would need and what you already have is a good starting point for your term insurance cover.
Use A Calculator And Understand Its Estimate
An online term insurance calculator can simplify this process. Typically, you enter details such as:
- Age, gender, and smoking habits
- Annual income
- Desired policy term (in years)
- Liabilities and basic expenses
The term insurance calculator then suggests:
- An approximate life cover amount
- An estimated term insurance premium for different plan options
Treat this result as a guide, not a final answer. Review whether:
- The coverage feels sufficient to protect your family’s lifestyle and goals
- The policy term is long enough to cover your main working years
- The premium fits comfortably within your budget today and in the future
You can tweak the inputs—cover amount, policy term, payout options—until you find a balance between the protection you want and the premium you can afford.
How DIME And Income Multiples Can Inform A Starting Figure
Two common approaches can help you arrive at a starting figure for your term insurance cover:
DIME method (Debt, Income, Mortgage, Education)
- Add all your debts and long-term loans.
- Add the income you would like to provide your family for a certain number of years.
- Add your home loan (if not fully counted already).
- Add the estimated cost of your children’s education.
The total gives a rough idea of the life cover your family may require.
Income multiple approachMany financial planners use a multiple of your annual income—often several times your yearly earnings—as a thumb rule for life cover.This is a broad guideline and should be refined using your actual liabilities, goals, and existing coverage.
Use these methods together with a term insurance calculator to arrive at a more personalised figure for your life insurance coverage needs.
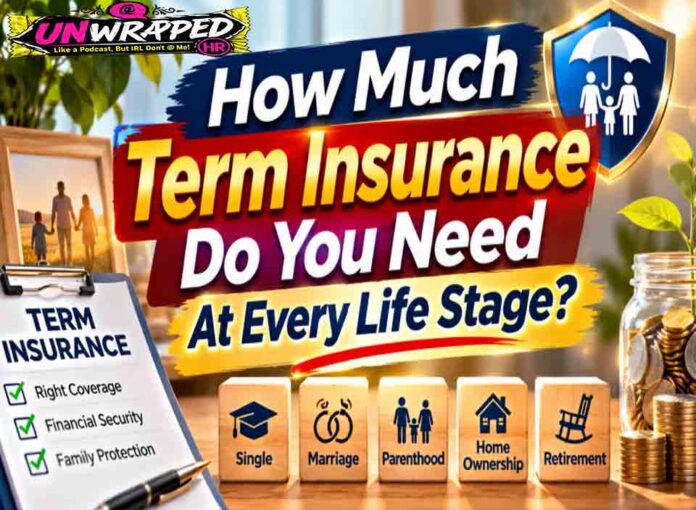
How Cover Needs Change Through Life Stages
Starting Work And Supporting Parents
In your early career, you may have fewer dependants but growing responsibilities such as:
- Supporting parents or siblings
- Starting to repay education loans or small personal loans
At this stage, you may not need a very high cover, but buying term insurance early can lock in a low premium for a long policy term. Consider:
- A cover that clears your loans and provides your dependants with basic financial support for a few years
- A policy term long enough to cover your expected working years
As your income rises, you can review and enhance your life cover.
Marriage, Children, And Growing Financial Commitments
This is often the most critical stage for term insurance for family protection. You may have:
- A spouse who relies on your income
- Young children with long-term education needs
- A home loan and other EMIs
Here, many people significantly increase their life cover. You may need:
- Higher coverage to replace your income for many years
- Additional amount to repay the home loan and other liabilities
- Extra buffer for children’s education and long-term goals
Review your term insurance cover whenever there is a major life event such as marriage, birth of a child, or taking a large loan.
Mid-Career Responsibilities And The Approach To Retirement
In mid-career, your income is often higher, but so are responsibilities. At the same time, you may:
- Have partly repaid your home loan
- Built some savings and investments
- Be closer to your planned retirement age
At this stage, you should:
- Check whether your cover still matches your family’s needs
- Consider whether your policy term extends close enough to your planned retirement
- Adjust your life cover if big loans are repaid or if your dependants are financially independent
You may not need to increase coverage every year, but you should review it regularly—ideally every few years or after any major financial change.
Compare Term Insurance Plans With Care
Compare Cover, Policy Term, Premium, And Payout Options
When you shortlist term insurance plans, compare the basics first:
- Life cover vs premium: For similar coverage and policy term, compare the annual premium. The cheapest is not always best, but you should get good value.
- Policy term: Ensure the term covers most of your earning years. Some may prefer coverage up to 60 or 65, others until specific goals are met.
- Payout options: Lump-sum, monthly income, or a combination. Think about what would help your family manage money comfortably.
A well-chosen term plan balances sufficient cover, a suitable policy term, and an affordable premium.
Review Insurer Disclosures, Exclusions, And Relevant Riders
Go beyond the headline premium and check:
- Key exclusions: Situations where the insurer may not pay the claim
- Waiting periods (if any riders specify them)
- Riders: Accidental death benefit, critical illness, waiver of premium, or disability riders can enhance your protection for a slightly higher premium
Always provide accurate health, lifestyle, and financial details in your proposal form. Full and honest disclosure helps protect your family’s claim later.
A Practical Checklist For Shortlisting A Plan
When choosing the best term insurance plan for your family, use a simple checklist:
- Does the estimated cover meet your family’s income, liabilities, and goal-based needs?
- Is the policy term aligned with your working years and major financial commitments?
- Is the term insurance premium affordable today and likely to remain manageable?
- Are the payout options and riders suitable for your family’s situation?
- Are you comfortable with the insurer’s service standards and disclosures?
Term insurance is the foundation of your family’s financial protection. Take time to calculate your cover carefully, use a term insurance calculator to fine-tune your numbers, and review your plan at every life stage so your loved ones, and their dreams, stay protected.